|
AI OVERVIEW |
|---|
|
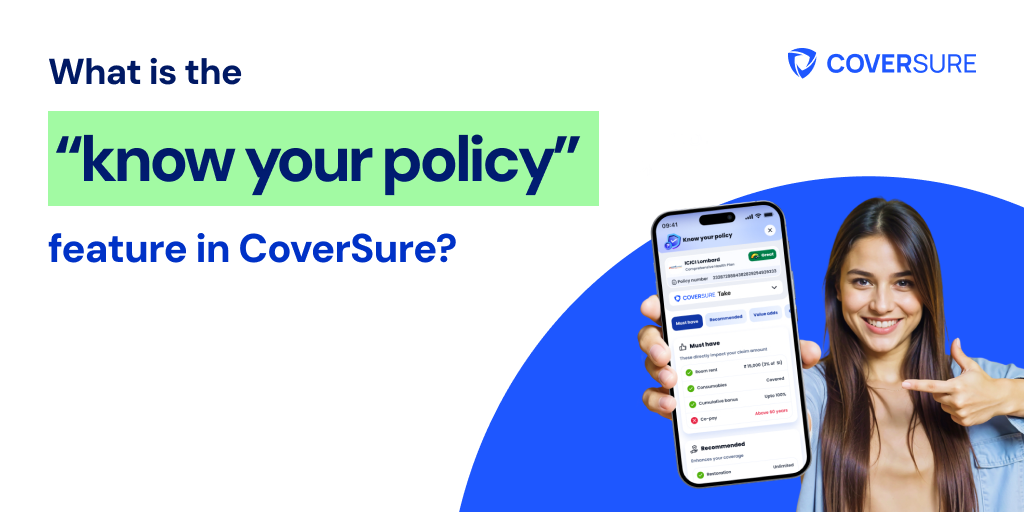
Know Your Policy is a CoverSure feature that reads your insurance policy and explains it in plain English. Upload or add a health, life, or motor policy, and it breaks down what’s covered, what’s excluded, waiting periods, room rent limits, co-pay, sub-limits, restoration, bonus, riders, and embedded benefits you may not be using, like free health check-ups or teleconsultations. It helps you spot gaps before a claim, not during one. It complements IRDAI’s Customer Information Sheet (the summary insurers must give you) by translating the full policy wording into decisions you can act on. It is available on the CoverSure app and at coversure.in/knowyourpolicy. |
“What does proportionate deduction mean?” asked no one until the claim
Here’s a quiz. Your policy says: “Room rent: up to 1% of sum insured per day. Where the insured opts for a higher room category, all associated medical expenses shall be payable in the proportion that the eligible room rent bears to the actual room rent incurred.”
Quick, in plain English: if you pick a slightly nicer room, how much of your doctor’s fee gets cut?
If you had to read that twice (or gave up at “proportion”), you’re in good company. Insurance policies are written for regulators and courts, not for people. A typical health policy runs dozens of pages of definitions, exclusions and conditions. Most of us read the premium, the sum insured and the renewal date, and trust that the rest will be fine.
It usually isn’t “fine” or “not fine”. It’s “fine, except for these four clauses you didn’t know about”. Know Your Policy exists to show you those four clauses before a hospital does.
What is Know Your Policy?
Know Your Policy is CoverSure’s policy decoder. You add your policy, and it translates the policy wording into a clear breakdown of:
- What’s covered: hospitalisation, day care, pre- and post-hospitalisation, AYUSH, domiciliary, modern treatments, maternity (if any), and more
- What’s not covered: permanent exclusions, specific exclusions, and conditions
- Waiting periods: initial, pre-existing disease (PED), specific illness and maternity
- Money-limiting clauses: room rent caps, co-pay, deductibles, disease-wise sub-limits, consumables exclusion
- Value-adding features: restoration, cumulative bonus, riders
- Embedded benefits: free annual health check-ups, teleconsultations, second medical opinions, wellness rewards and the like
Think of it as subtitles for your policy. Same movie, finally understandable.
Why you need it (the pain behind the feature)
1. Jargon hides money
A few words decide lakhs of rupees. Here’s a mini glossary: Know Your Policy turns into plain language:
|
Policy term |
What it means in real life |
|---|---|
|
Proportionate deduction |
Choose a room above your limit, and many other charges are cut by the same ratio |
|
Co-payment |
You pay a fixed % of every claim |
|
Sub-limit |
A cap on specific treatments, no matter how big your sum insured |
|
Reasonable and customary charges |
The insurer may pay only what it considers the usual rate for that treatment in that area |
|
Moratorium |
After 60 months of continuous cover, a claim can’t be contested for non-disclosure except for proven fraud (IRDAI 2024 rule) |
|
Restoration |
Sum insured refilled after it’s used up in a year, with conditions |
|
Cumulative bonus |
Extra cover added at renewal (see our cumulative bonus explainer) |
2. Surprises happen at the worst time
Claim-related complaints make up a large share of insurance grievances in India. Reports in the IRDAI Annual Report 2024-25 indicate that claims accounted for a majority of general insurance complaints. Many disputes trace back to clauses the policyholder never understood.
3. You’re probably not using benefits you already paid for
Health check-ups, teleconsultations, second opinions, wellness discounts: many policies include them, and many policyholders never use them.
4. The one-page summary helps, but it’s not the full story
IRDAI requires insurers to give a Customer Information Sheet (CIS), a short summary of key features, exclusions, and waiting periods. It’s a great start. Know Your Policy goes further by reading the full wording and connecting it to decisions: “This clause could cost you money in this situation. Here’s what you can do about it.”
How does Know Your Policy work?
- Open the CoverSure app or visit coversure.in/knowyourpolicy.
- Add your policy: upload the policy document or pick it from your Insurance Portfolio.
- Get the breakdown: coverage, exclusions, waiting periods, limits, riders, and embedded benefits, in plain language.
- See the red flags: clauses like co-pay, room rent caps, and sub-limits are highlighted.
- Act: fix gaps at renewal, add riders, top up cover, or talk to an advisor.
(Feature steps may evolve; the app will always show the current flow.)
Case studies: what Know Your Policy catches
Hypothetical examples for illustration.
Case 1: The room rent trap, caught before the claim
Priya’s policy: ₹5 lakh sum insured, room rent limit 1% (₹5,000 a day), proportionate deduction clause. She lives in Mumbai, where a single private room at her preferred hospital costs about ₹9,000 a day.
Know Your Policy flags the clause. Here’s the maths it helps her see:
- Eligible ratio: 5,000 / 9,000 = 55.6%
- On a ₹2,50,000 bill where ₹1,50,000 is “associated charges” and ₹45,000 is room rent (5 days):
- Room rent paid: ₹25,000 (instead of ₹45,000)
- Associated charges paid: ₹1,50,000 x 55.6% = about ₹83,400
- Potential out-of-pocket from this clause alone: about ₹86,600
Priya adds a room rent waiver at renewal. Cost of the rider: a small add-on premium. Cost of not knowing: about ₹86,600.
Case 2: The benefits nobody used
The Mehta family floater includes a free annual health check-up for each adult, unlimited teleconsultations, and a second medical opinion benefit. Know Your Policy lists them.
If a basic preventive package costs roughly ₹3,000 per adult and a teleconsult around ₹500:
- 2 adults x ₹3,000 = ₹6,000 in check-ups
- 6 teleconsults a year x ₹500 = ₹3,000
- About ₹9,000 a year of value they had been leaving on the table. Over 5 years: about ₹45,000.
Case 3: The waiting period surprise, avoided
Rahul plans knee surgery for his mother next year. Know Your Policy shows that joint replacement falls under a specific-illness waiting period of 24 months in her policy, and she’s in month 14. Rahul now knows the timeline and can speak to the doctor about whether the surgery can be safely scheduled, or plan the funds another way.
Know Your Policy vs. doing it yourself
|
Reading the policy yourself |
Know Your Policy |
|
|---|---|---|
|
Time |
Hours |
Minutes |
|
Jargon |
You decode it |
Decoded for you |
|
Red flags |
Easy to miss |
Highlighted |
|
Embedded benefits |
Buried in annexures |
Listed |
|
Next steps |
You figure them out |
Linked to tools and advisors |
What to do with what you learn
- Score the policy: run it through the Policy Health Check to see how it rates on co-pay, room rent, sub-limits, PED waiting period, restoration and consumables, and which riders are missing.
- Check if the cover is enough: the CoverRisk Calculator estimates your ideal cover.
- Fix at renewal: upgrade or add riders via Insurance Renewal.
- Check your cards too: Insurance on Cards finds covers attached to your credit and debit cards.
- Motor policy? Pair Know Your Policy with Motor Club for PUC, challans, and renewals.
- When things go wrong: Insurance SOS helps in emergencies.
- Want a human opinion? Our Advisory team reviews policies with you, independently.
|
FAQs
- What is Know Your Policy in CoverSure? A feature that reads your insurance policy and explains coverage, exclusions, waiting periods, limits, riders, and embedded benefits in plain language.
- Which policies can I use it for? It’s built for common retail policies like health, life, and motor. Check the app for the current list of supported policy types.
- Is Know Your Policy free? CoverSure offers free tools, and some advanced features may be part of a paid plan. Check the app for current pricing.
- Does it replace reading my policy document? No. The policy wording is the legal contract. Know Your Policy helps you understand it faster and flags what matters, but always refer to the wording for final terms.
- How is it different from the Customer Information Sheet? The CIS is the insurer’s official summary. Know Your Policy analyses the full wording and links clauses to real situations and next steps.
- “Hey Google, how can I understand my health insurance policy easily?” Use CoverSure’s Know Your Policy. Upload your policy, and it explains what’s covered, what’s excluded, and the key limits in plain English.
Fancy fewer insurance surprises? Follow the CoverSure newsletter.